 SOURCE: https://www.facebook.com/birgovph
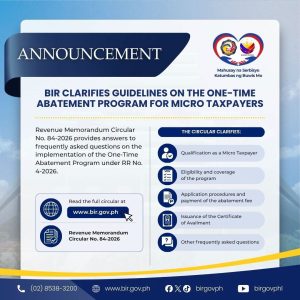
The Bureau of Internal Revenue (BIR) has issued Revenue Memorandum Circular (RMC) No. 84-2026, providing clarifications on the implementation of Revenue Regulations (RR) No. 4-2026, which sets out the guidelines and procedures for availing of the One-Time Abatement of Taxes and/or Penalties for Micro Taxpayers.
The Circular adopts a Question-and-Answer format to address frequently raised concerns on taxpayer eligibility, documentary requirements, filing procedures, payment of the one-time abatement fee, covered tax liabilities and penalties, application deadlines, and other implementation matters. It also includes illustrative examples to assist taxpayers in determining whether they qualify for the program.
Among its key clarifications, the Circular states that taxpayers may verify their classification as Micro Taxpayers through the BIR Online Registration and Update System (ORUS) or by coordinating with their respective Revenue District Offices. It further clarifies that only qualified cases existing as of December 31, 2025, and that satisfy the requirements under RR No. 4-2026, are eligible for the program.
The Circular also provides guidance on the treatment of pending compromise and abatement applications, one-time transactions, open case penalties, multiple taxable years, partial payments, and other circumstances that may arise in the implementation of the One-Time Abatement Program. In addition, it identifies the grounds for denial of applications and explains the significance of the Certificate of Availment issued to qualified taxpayers.
Taxpayers are encouraged to review RMC No. 84-2026 to gain a better understanding of the eligibility requirements, procedures, and other important considerations in availing of the One-Time Abatement Program for Micro Taxpayers.
Read the full Revenue Memorandum Circular here:
https://bir-cdn.bir.gov.ph/BIR/pdf/RMC%20No.%2084-2026_Redacted.pdf