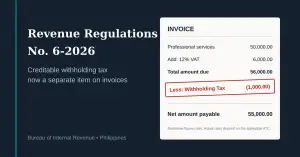
 an invoice showing the creditable withholding tax as its own line.
Quick summary
The Bureau of Internal Revenue (BIR) issued Revenue Regulations (RR) No. 6-2026, which requires the amount of creditable withholding tax (CWT), when applicable, to appear as a separate item on invoices. GMA News reports that the regulation was signed by Finance Secretary Frederick Go and published by the BIR on October 1, 2026. It does not create a new tax or a new withholding rate. It changes what an invoice must show.
What RR No. 6-2026 changes
The regulation, titled Amending the Mandatory Information Contained in the Invoice Pursuant to Section 6(B) of Revenue Regulations No. 07-2024 to Include Creditable Withholding Tax Information, adds one new required entry (item 22) to the list of invoice information. According to the BIR’s published copy of RR No. 6-2026, it is issued under Sections 244 and 245 of the National Internal Revenue Code of 1997, as amended (Tax Code), in relation to Section 47 of Republic Act No. 11976, the Ease of Paying Taxes (EOPT) Act.
In practice:
- The CWT amount must be a number on its own line, not a note buried in the description.
- The requirement applies “if applicable,” meaning transactions where creditable withholding tax actually applies.
- The BIR says the goal is making withheld amounts easy to identify and verify. Commissioner Charlito Martin Mendoza said that proper documentation reduces confusion and helps both parties comply.
Background: RR 7-2024 and the EOPT Act
RR No. 7-2024 implemented the invoicing provisions of the EOPT Act (RA 11976). As summarized by KPMG, the EOPT Act made the invoice the primary document for sales of both goods and services, so official receipts are no longer the primary evidence of a sale. Forvis Mazars and Grant Thornton Philippines describe how later issuances, such as RR No. 11-2024, extended transition deadlines and allowed conversion of unused official receipts.
RR No. 6-2026 builds on that framework. It leaves the invoice-first system intact and adds one more data point to the invoice.
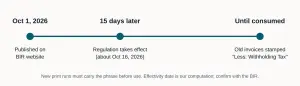 Original timeline graphic based on Sections 3 and 6 of RR No. 6-2026
Effectivity and transition rule
When does it take effect?
Section 6 of the regulation says it takes effect fifteen (15) days after publication in the Official Gazette or on the BIR website, whichever comes first. Several outlets, including Daily Guardian, report publication on October 1, 2026. Counting 15 days, that points to about October 16, 2026. This is our own computation, so confirm the date on the BIR’s issuance page before relying on it.
What happens to invoices you already have?
Section 3 of the regulation provides that unused or unissued invoices existing on the effectivity date may continue to be used until fully consumed, provided the phrase “Less: Withholding Tax” is stamped conspicuously on the face of the invoice. Newly printed invoices must carry the same phrase before use. Radar PH stresses that the rule focuses on clearer reporting and does not impose a new withholding rate.
Situation | What to do |
Unused invoices in stock on the effectivity date | Keep using them; stamp “Less: Withholding Tax” conspicuously on the face. |
New print run or new system template | Include the phrase and a separate CWT line before use. |
Transaction subject to CWT | Show the CWT amount as a separate item. |
Worked example
The figures below are fictional. The 2% rate is an assumption for illustration; the actual rate depends on the payee’s income classification, the applicable Alphanumeric Tax Code (ATC), and current regulations.
Invoice line | Amount (PHP) |
Professional services | 50,000.00 |
Add: 12% VAT | 6,000.00 |
Total amount due | 56,000.00 |
Less: Withholding Tax (assumed 2% of 50,000) | (1,000.00) |
Net amount payable | 55,000.00 |
The red line is the separate item the regulation calls for. The seller records PHP 1,000 as creditable tax to claim against income tax once the buyer’s certificate is received.
Note: The regulation does not say how to treat the line when the withholding amount is not yet known at invoicing. Consult your Revenue District Office (RDO) or a licensed tax professional for that situation.
Invoice line vs. BIR Form 2307
RR No. 6-2026 does not replace BIR Form 2307 (Certificate of Creditable Tax Withheld at Source), which the withholding agent issues to the payee. It also does not change who issues the certificate or when. The new rule simply gives both parties a second place to see the same number. As BIR Online Tools notes, the amount on the invoice should tie to the amount on the certificate, which makes quarter-end reconciliation easier.
Compliance checklist
For sellers and professionals
- Confirm the effectivity date on the BIR’s issuance page.
- Count unused invoice booklets and stamp “Less: Withholding Tax” on those still in use.
- Update billing, POS, and e-invoicing templates so the CWT amount has its own line.
- Include the phrase in your next print order.
For buyers and withholding agents
- Check that supplier invoices show the CWT line and that it matches your computation.
- Reconcile each invoice against the BIR Form 2307 you issue.
- Apply the correct ATC and rate, since the rule changes disclosure, not the rate.
For accountants and finance teams
- Brief clients and update invoice review procedures and accounting-system mappings.
- Keep a copy of the BIR’s published regulation in your compliance file.
- Watch for BIR Revenue Memorandum Circulars that may clarify implementation.
Frequently asked questions
What does BIR RR No. 6-2026 require?
It adds the amount of creditable withholding tax, if applicable, as a separate item among the mandatory information on invoices under Section 6(B) of RR No. 7-2024.
Do I need to discard my unused invoices?
No. You may use them until fully consumed, as long as “Less: Withholding Tax” is conspicuously stamped on the face.
Does this create a new withholding tax?
No. Per reports from Radar PH, the regulation does not impose a new withholding rate.
Does it replace BIR Form 2307?
No. Form 2307 remains the certificate issued by the withholding agent to the payee.
Conclusion
RR No. 6-2026 is a short regulation with a clear message: withholding tax should be visible on the invoice. Businesses should stamp or update their invoices now, align their templates, and reconcile invoice lines with BIR Form 2307. For professional-body guidance, also check announcements from the Philippine Institute of Certified Public Accountants (PICPA), the Association of Certified Public Accountants in Public Practice (ACPAPP), the Board of Accountancy, and the Professional Regulation Commission (PRC).
Sources and references
- Bureau of Internal Revenue, Revenue Regulations No. 6-2026 (official PDF)
- GMA News, BIR requires amount of withholding tax to be shown as separate item on invoices
- Daily Guardian, BIR requires withholding tax shown separately on invoices (Oct. 13, 2026)
- Radar PH, BIR now requires businesses to separately show withholding tax on invoices
- The Morning Standard, BIR fires transparency shot (Oct. 12, 2026)
- BIR Online Tools, RR No. 6-2026: Invoices Must Now Show Creditable Withholding Tax as a Separate Item
- KPMG, Philippines: Updated invoicing requirements
- Forvis Mazars Philippines, VAT Invoicing Requirements and Transitory Provisions Under the EOPT Act
- Grant Thornton Philippines, Amendments and extension of deadlines for invoicing requirements under the EOPT Act
This article is for general information only and is not legal or tax advice. Verify the effectivity date and your specific situation with the BIR or a licensed tax professional.