 BIR clarifies withholding tax obligations for electricity sales through WESM.
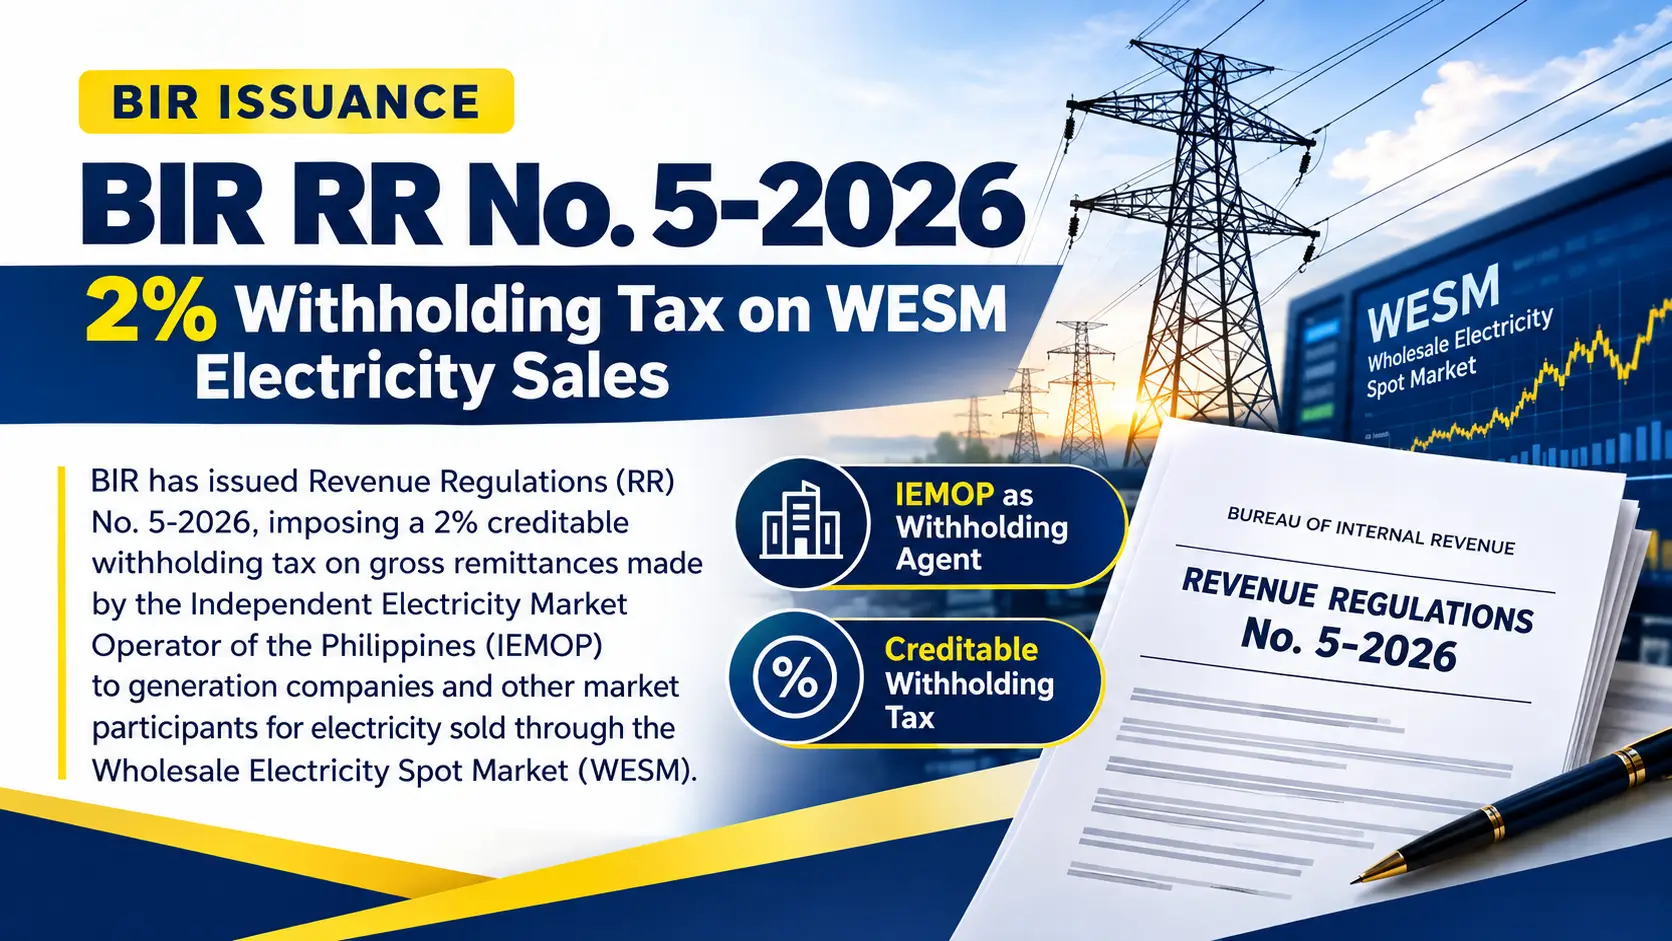
The Bureau of Internal Revenue (BIR) has issued Revenue Regulations (RR) No. 5-2026, further amending the withholding tax provisions under RR No. 2-98, as amended, to impose a 2% creditable withholding tax on gross remittances made by the Independent Electricity Market Operator of the Philippines (IEMOP) to generation companies and other market participants for electricity sold through the Wholesale Electricity Spot Market (WESM).
Under the new regulations, IEMOP is designated as a withholding agent responsible for deducting and withholding the applicable 2% tax on gross remittances to electricity sellers. These remittances refer to the total amount payable for electricity sales before any deductions.
The regulations clarify that IEMOP acts solely as a withholding agent and is not considered to earn income from the remittances covered by the issuance.
Withholding and Reporting Responsibilities
As the designated withholding agent, IEMOP must comply with the following obligations:
Withhold the applicable tax. Deduct and withhold 2% creditable withholding tax from gross remittances to generation companies and other market participants for electricity sold through WESM.
Remit withheld taxes. File and pay the withheld taxes through the BIR’s Electronic Filing and Payment System (eFPS), together with the required Alphabetical List of Payees submitted through the eSubmission system, in accordance with existing BIR rules and deadlines.
Issue withholding tax certificates. Provide each electricity seller subject to withholding with a Certificate of Tax Withheld at Source (BIR Form No. 2307) on or before the 20th day after the close of the taxable quarter, or upon the payee’s request.
Submit the required quarterly list. Furnish the Large Taxpayers Service’s LT Document Processing and Quality Assurance Division with a duly certified list of electricity buyers under Annex “A” on or before the last day of the month following the close of each taxable quarter.
Amendment to Existing BIR Regulations
RR No. 5-2026 further amends Section 2.57.2 of RR No. 2-98, as amended, which covers income payments subject to creditable withholding tax and the corresponding rates. The new provisions establish the withholding tax treatment for gross remittances made through IEMOP for electricity transactions conducted in WESM.
The regulations also provide that existing rules and issuances inconsistent with the new provisions shall be repealed, amended, or modified accordingly.
Effectivity
RR No. 5-2026 takes effect 15 days following its publication in the Official Gazette or on the official BIR website, whichever comes first.
Electricity market participants and other concerned parties should review the regulation and coordinate with their tax and accounting teams to ensure compliance with the applicable withholding, remittance, certification, and reporting requirements.
Reference: BIR Revenue Regulations No. 5-2026 (Official PDF)